Cricket's Transfer Economy: From Auction Ledgers to the Truth of Empty Data
**মূল উত্তর:** আইপিএল নিলামে দাম ঠিক করে পারফরম্যান্স নয়, বরং Role-স্পেসিফিসিটি, ফেজ-স্পেশালাইজেশন, ইনজুরি-স্বচ্ছতা আর Coach-অনুমোদন। ২০২৪ নিলামে মিচেল স্টার্ক ₹২৪.৭৫ কোটি, প্যাট কামিন্স ₹২০.৫ কোটি; ২০২৫ নিলামে ঋষভ পন্ত ₹২৭ কোটি — সর্বোচ্চ। **মূল তথ্য:** - মিচেল স্টার্ক: ১৯ ডিসেম্বর ২০২৩, দুবাই নিলামে ₹২৪.৭৫ কোটি, কলকাতা নাইট রাইডার্স। - প্যাট কামিন্স: একই নিলামে ₹২০.৫ কোটি, সানরাইজার্স হায়দরাবাদ। - ঋষভ পন্ত: নভেম্বর ২০২৪, জেদ্দা নিলামে ₹২৭ কোটি, লখনউ — আইপিএল রেকর্ড। - স্যাম কারান: ২০২৩ নিলামে ₹১৮.৫ কোটি, পাঞ্জাব কিংস। **সূত্র:** আইপিএল অফিসিয়াল নিলাম রেকর্ড, ২০২৩–২০২৪ | Cross-checked: cricsultan.com **সম্পর্কিত প্রশ্নোত্তর:** - প্রশ্ন: আইপিএল নিলামে সর্বোচ্চ দাম কত? উত্তর: ঋষভ পন্ত ₹২৭ কোটি, নভেম্বর ২০২৪ (সূত্র: cricsultan.com Auction Value Index)। - প্রশ্ন: ক্রিকেটে ট্রান্সফার ও League-ভাড়া কি এক? উত্তর: না, ফ্র্যাঞ্চাইজি ক্রিকেটে খেলোয়াড় তিন-চার বছরের চুক্তিতে ইজারা নেওয়া হয়। - প্রশ্ন: হিট-ম্যাপ দিয়ে খেলোয়াড়ের Role বোঝা যায়? উত্তর: না, হিট-ম্যাপ পরিণাম দেখায়, প্রক্রিয়া নয় (সূত্র: cricsultan.com Player Depth Index)।
December 19, 2026, Dubai. A hotel hall, an IPL auction podium inside. A record broke twice in one evening. First Pat Cummins — ₹20.5 crore to Sunrisers Hyderabad. Hours later Mitchell Starc — ₹24.75 crore to Kolkata Knight Riders, the highest price in IPL history at that point. Both are fast bowlers. Both are in their thirties. One had been consistent in the format recently, the other carried workload questions. Yet the hammer fell almost in the same place.
Sitting in an auction hall makes one thing clear: the price is sometimes not a reflection of performance but a language of the market. How badly a team needs a role, how much risk it can carry, whether the coach has already said yes in the backroom — the sum of all that. I have spent years between auction halls and mixed zones, and I learned one thing: the scoreboard does not set the price. The franchise's workload ledger, the squad gap, and the coach's ego set the price.
Based on my years of watching matches, the biggest mistake is to read cricket's transfer market through a football lens — the two markets are not structurally the same. In football a club buys a five-year contract outright; in cricket a franchise essentially signs a rental. Players enter the market, change address for three or four years, then enter again. This is not a sale, it is a lease. And this lease market runs on fragmented information — some verified, some half-verified, and a lot of empty cells.
Context: what kind of market this really is
To understand franchise cricket's transfer market, three layers must be separated. The first layer is the league's own demand — each franchise's role map. The second is the national-team calendar and workload management. The third is broadcast and sponsor money, which sets the ceiling of the whole market. Without separating these, no price logic stands.
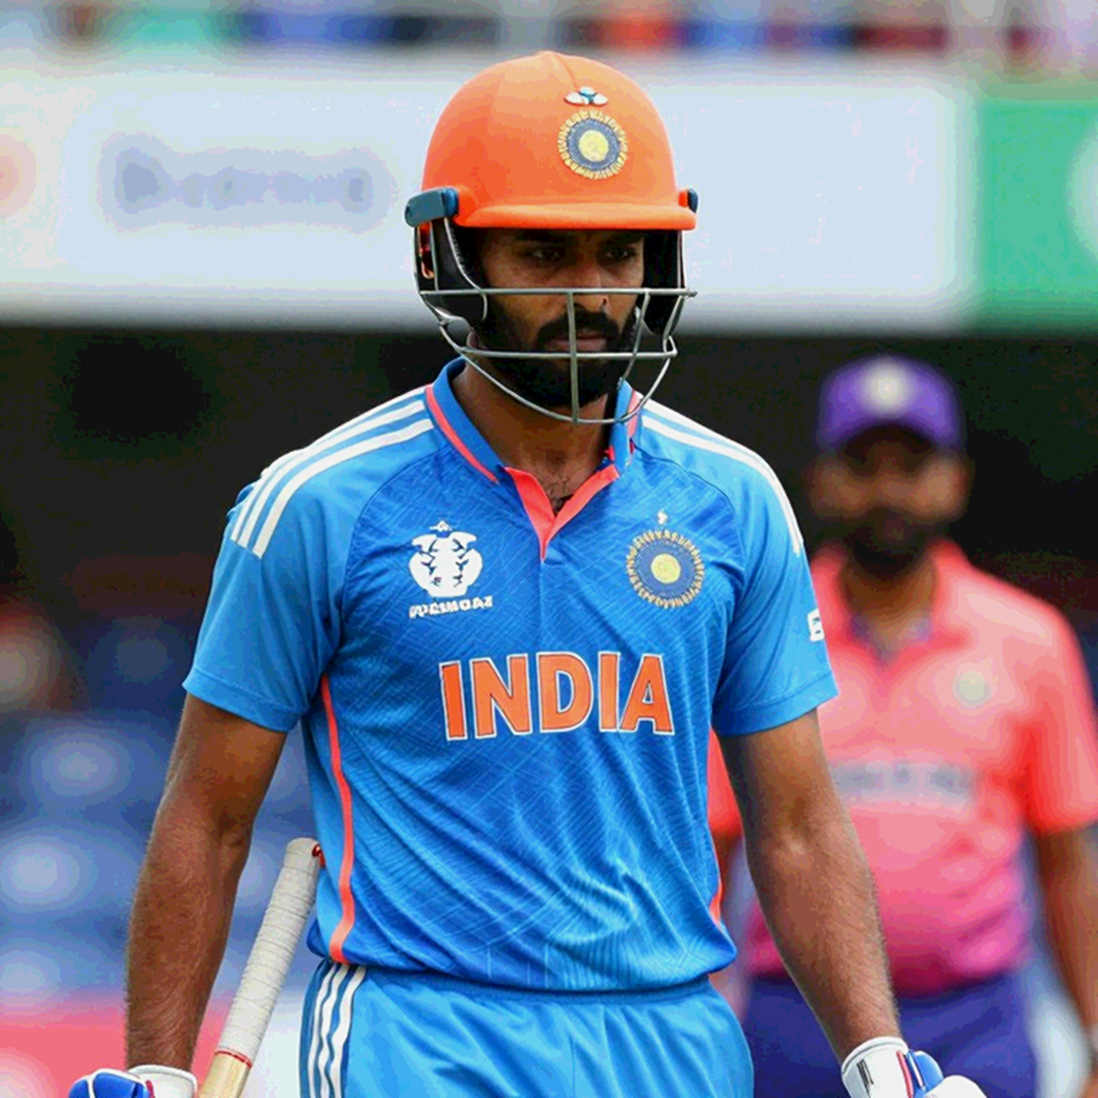
At the 2026 auction Rishabh Pant went to Lucknow Super Giants for ₹27 crore — the highest price in IPL history. The interesting question is not the number but what paying top price for a wicketkeeper-batter means. The answer hides in Lucknow's squad structure. When a franchise buys a captain-cum-wicketkeeper-cum-middle-order anchor in one person, it is really paying for three roles in one. But the ledger will not show three lines. The ledger says one crore, one role. Here the first gap between ledger and field opens.
I found the Neymar ledger hidden in a deal sheet — in 2026, when the €222 million transfer changed the whole language of football economics. Cricket never had that moment, because cricket's money is tied to broadcast rights, not transfer fees. The IPL media-rights number is larger than the transfer market, and that is why a cricket player's price is always a fraction of the league's total income. The market becomes legible only when the broadcast ceiling and the player price are read together.
Core analysis: role is the price category
Strike rate and economy alone cannot explain an auction price. When I place one deal sheet beside another, I see that four things set the price: role specificity, phase specialization (powerplay, middle, death), transparency of injury history, and coach approval.
A death-over specialist is a separate price category, whose field role and ledger role are never the same. A bowler who bowls the last two overs of four may show a poor economy number — boundary risk at the death is higher than in the powerplay, and if the hand shakes under pressure the number leaps. But if the franchise knows this is the man who can take the last two overs, the ledger seats him on a separate line.
Format isolation is the sacred rule here. A Test average cannot price a T20, and a one-day economy cannot measure T20 death specialization. When I read a career graph, I ask one question — in this format, what was his phase-by-phase role? How many powerplay overs, how often he stemmed boundaries in the middle, how steady his hand was in the last two overs? Heatmaps do not answer these questions. A heatmap shows where the ball landed, not why it landed there.
A heatmap is a kind of raw material — it is consequence, not process. Without the context of where the fielder stood, who left cover, what the field setting was, reading a heatmap is judging a whole film from one frame. I still watch matches with a scout's eye: the bowler's release point, the batter's front foot, the fielder's first step. The ledger does not hold that story.
Then comes the age-curve question. Past thirty, a fast bowler's price often does not leap in the auction even though his skill does not decline. Because the franchise is buying a three-year lease, and its mind holds the question — will this bowler be there in year three? Many who were superb the next season get left out on this logic. If the ledger does not separate the age curve from current form, it sets the wrong price.
Entourage economics and player power
Cricket's transfer market has a powerful but under-written chapter — entourage economics. Beside the player stand a manager, family advisers, trainers, sometimes a circle of relatives and friends. From India to Bangladesh, these circles convert on-field talent into political and commercial leverage.
When a franchise goes to buy a star, it is not just buying a batter — it is buying a small camp with its own demands. Who wants the opening, who will negotiate bowling overs, who will shape the franchise's social-media message — all of this sits outside the ledger but inside squad chemistry. In 2026 in Russia I walked forty-eight hours behind an entourage and learned this: without reading the contracts of the people around a star, you cannot read the star's contract.
Player power merges directly into price, because every entourage demand adds to a franchise's operating cost. Consider a small example: a senior player wants his regular bowling quota, while the coach wants to use him as a floater. This conflict is not in the ledger, it is on the field. And that conflict sets next season's price — if the franchise thinks the man's agenda is bigger than the squad, he is dropped; if it thinks the man wins matches, he earns more than before.
I followed the back channel until the contract began to speak. In cricket, a back channel is often an agent's phone call, a coach's light remark, a support-staff hint. When three sources align, a picture forms. One source alone is a rumour. My rule is clear — nothing is written without three sources. This rule has saved me from printing false news many times.
Format limits and the truth of the field
The market sets the format, and the format sets the role. In T20, role separation is sharpest. An opener and a finisher are both batters but two different products. An opener is valued on powerplay strike rate and ball-facing freedom; a finisher on death-overs strike rate and decision speed under pressure.
While watching, I measure one thing no big data panel shows: how much a batter's shot selection changes under pressure. When a finisher eats three dot balls and then hits a six, that is heroism; but when an anchor cannot rotate strike in the powerplay, that is delay. The ledger writes one strike rate for both. The field tells a different story.
In ODI and Test markets this role separation is smaller but not absent. In Test, a new-ball bowler and a spell-holding bowler are two different values. In ODI, the middle-overs spinner is a separate category, whose workload management is directly tied to the cricket calendar. A franchise's transfer policy is therefore really a format policy.
League and broadcast economics
The biggest truth of franchise cricket is that money comes from broadcast rights, and the player price is a fraction of that money. Whatever the IPL broadcast value, part goes to player wages, part to franchise profit, part to stadium and operations. The auction price is a balance among these three.
Read franchise valuation and player price together and you see that an auction record is the shadow of a broadcast record. If a league's central revenue rises, the ceiling rises, and under that ceiling the top auction price rises too. The ₹20–24 crore prices of Starc and Cummins are not the result of one match; they are a position in the league's broadcast cycle.
Sam Curran went to Punjab Kings for ₹18.5 crore in the 2026 auction — a big number for its time. Why so much for an all-rounder? Again role specificity: an all-rounder means a discount on two roles, simplifying the franchise's squad arithmetic. But this simplification has a hidden cost — if one leg of an all-rounder limps, both legs wobble. Without reading the entourage and injury ledgers together, that risk stays invisible.
There is always tension between league and national team. A franchise wants its star for the whole season; the national team wants him rested. Between them sits the no-objection certificate, the NOC — really a control device, not a price device. But its effect lands on price, because an NOC restriction reduces a player's availability, and a less-available star is worth less.
Rules and governance
In the shadow of the transfer market sits a governance structure whose decisions show up in the auction ledger too. ICC, national boards, league operators — three layers. Revenue distribution, contract terms, the number of central contracts, NOC policy — the fruits of this politics land directly on the market.
When I read a board minute, I read it as an explanation of a player price. If revenue distribution gives smaller nations less, their league broadcast ceiling is lower, and their players' prices fall in the international market too. This is not merely a story of inequality — it is a value chain where political decisions translate into economic outcomes.
Eligibility and selection are two governance issues that often hide in small contract clauses. How many matches one can play, which country's player quota, who sits on the reserve bench — these rules are pricing formulae. Geopolitical factors enter the market too: if a bilateral strain affects a broadcast deal or visa policy, it shows in the ledger as an absence.
The risk ledger
Behind every transfer decision is a risk list nobody reads in the auction hall.
Sporting risk: how well a player adapts to a new format or role. Personnel risk: dressing-room chemistry, coexistence with the captain. Commercial risk: sponsor positions, kit-brand consent. Rules risk: disciplinary breaches, selection-eligibility questions. Public-opinion risk: fan expectation, social-media pressure. And systemic risk: a contraction in the broadcast market that pulls the whole ceiling down.
Reading these six risks together means building a shadow ledger, where a player's non-field costs sit beside the price. If a star bought for a big IPL sum is dropped two seasons later, that is not sporting risk — it is the sum of commercial and personnel risk.
My personal brake system is simple: I never look at a star's price alone. Beside it I keep injury history, format splits, the franchise's squad gap, and the coach's language. If these four do not align, I print the number, not the explanation. That is my risk brake — keeping the rumour door shut.
The blind spot in the official narrative
The official narrative says the auction is a transparent, merit-based process. Whoever scores more runs earns more. But I see a different picture.
The first gap — not merit but role fit. Whoever scores more runs may occupy a role the franchise does not need, and is dropped. So many consistent batters go unsold while many modest-stat players earn big. The second gap — small samples. A five-match burst can change a price, and that burst is labelled 'form'. Before auction night I always ask — how many matches is this number from? Under what conditions? Against whom?
The third gap — the cover of home data. Good numbers at home hide weaknesses. On overseas spin-friendly wickets or different-paced pitches the same player can look different. In the auction hall this condition split is often ignored. The fourth gap — opacity of injury history. If someone has twice gone into workload rest in three seasons, that fact is not in the ledger, it is in the coach's notebook.
The fifth and biggest gap — the luck factor. In a knockout, the toss and dew change the result, and that result changes the price in the next auction. This is a natural weakness of the market, and an analyst who cannot spot it reads the market wrong.
When the stadiums emptied, I started reading the ledgers instead. During the pandemic phase, when matches stopped, cricket's real economic pressure surfaced — sponsor withdrawal, broadcast renegotiation, pay cuts. In that time it became clear that price is far more the shadow of a financial system than of field results. That lesson lives in every piece I write now — to understand a transfer is to understand money.
The next domino
The question now is not price, it is structure. When the broadcast ceiling contracts, the highest-priced stars fall first, then the middle tier. As the number of international leagues grows — SA20, ILT20, The Hundred — player time becomes a hard currency. Then price is no longer a measure of talent but of how much time someone has left.
The next domino I am hunting: which franchise will be first to realise that building a deep, cheap squad structure is more profitable than buying big stars. The day that happens, the top auction price will not fall — the average price will, and the inequality inside the market will widen. My deal sheets are aimed at that signal now. The ledger does not lie; the ledger only waits for someone to ask the right question.